Metal markets may be fragmenting but for the emergent global mining technology sector the dominant trend is convergence. Experienced mining leader Laura Tyler said at a big 2025 mining event in Australia computational power, AI and robotics had moved society and industry to the “next portal of development and discovery”.
Automation and robotics were set to change today’s work and workplaces. New scientific revolutions could potentially change “how we extract resources tomorrow”, she said.
But it is not just technological confluence creating a foundation for mining and metals technology firms to become more influential and more investible.
The industry is seeing, finally, a coming together of capital markets and mining and metals tech. Traditional equipment manufacturers are bolting on tech and tech companies. And mining’s widening public aperture is increasing scrutiny of its operational deficiencies and vulnerabilities – energy, water, sub-surface insight, health and safety are just a few of the areas – and the technology available to address them.
Add geopolitics and the race to build, or rebuild, sovereign industrial capability to this mix and the momentum behind a nascent mining and metals tech sector is unmistakable. “We’re just beginning the broader critical minerals super cycle,” Orion Industrial Ventures managing partner Mark Frayman said at Australia’s IMARC conference in October. OIV has just closed its first minerals, materials and energy tech fund. “It’s [minerals] at the forefront of all geopolitical discussions globally. We'll see technology and technology access, much like it is in semiconductors, become really strategic and the leading start-ups will get government funding. We’ll start to see really large influxes of capital come into the sector.”
Frayman said this month innovation was a key to “identifying, developing and operating natural resource assets at viable economics and in a sustainable way”.
“We believe the emerging companies developing these technologies today will scale into the leading mining and mining service companies of tomorrow,” he said.
Mining and metals technology is not yet recognised – by investors, government or even the mining industry itself – as a separate stratum of the circa-US$200 billion-a-year mining equipment, technology and services (METS) vertical.
However, there are clear trends moving the sector to a new level of prominence, among them the repositioning of METS majors as tech companies rather than equipment or service entities.
Major themes elevating the profile of mining and metals tech in 2026 are:
Surging tech financing and M&A
Growth in demand for automation, operational edge control and AI in mining
Increased material recycling and mine tailings reprocessing
Geopolitics and sovereign supply chains
Water pressures and scarcity
Biotech and AI convergence
New public mining and metals tech champions
A critical need for greater sub-surface visibility and insight
Coarse ore grinding and flotation breakthroughs
OEMs using tech to grow the aftermarket pie
Show me the money
Circa-US$15 billion of mining and metals technology financing and M&A from 2021 to 2025 is a drop in the proverbial ocean of global tech deals in that time but is unprecedented for the niche space.
Last year produced a new high watermark for mining and metals tech deal-making with more than $4.8 billion of transactions beating the previous record level of $3.03 billion in 2021 when Bentley Systems paid more than $1 billion for Seequent and Sandvik bought Deswik in another sector megadeal.
London-listed Weir shelled out $800 million and US-based Caterpillar $735 million for Australian mining software firms, Micromine and RPMGlobal, respectively. Pittsburgh-headquartered Wabtec Corporation paid $1.78 billion for Evident Scientific Inspection Technologies to bolster its digital rail, mining and industrial maintenance business.
Software and sensor-focused M&A accounted for about 90% of mining and metals tech corporate transactions in 2025. Six Australian software and sensor companies worth more than $1.6 billion were acquired in 2025. Australia’s Maptek represents a potential big-ticket acquisition still on the table.
Nearly $1.2 billion of venture financing entered the mining and metals tech space in 2025, with almost half that coming from US investors and investment firms including 16% from Silicon Valley.
More than one-third of over 130 investors in 2025 mining and metals tech financings had a cleantech investment focus.
Eleven mining and oil companies invested in mining and metals tech in 2025, along with five vehicle manufacturers. Mining major BHP was busiest on the deal front, through its corporate venture capital arm, though Rio Tinto, Bill Gates-founded Breakthrough Energy Ventures and CIA-backed In-Q-Tel (IQT) weren’t far behind.
Frayman said he understood three of the first seven investments made by Breakthrough’s newest fund were aimed at critical minerals, “which is quite incredible given the breadth of their mandate”.
AI puts autonomy on the edge
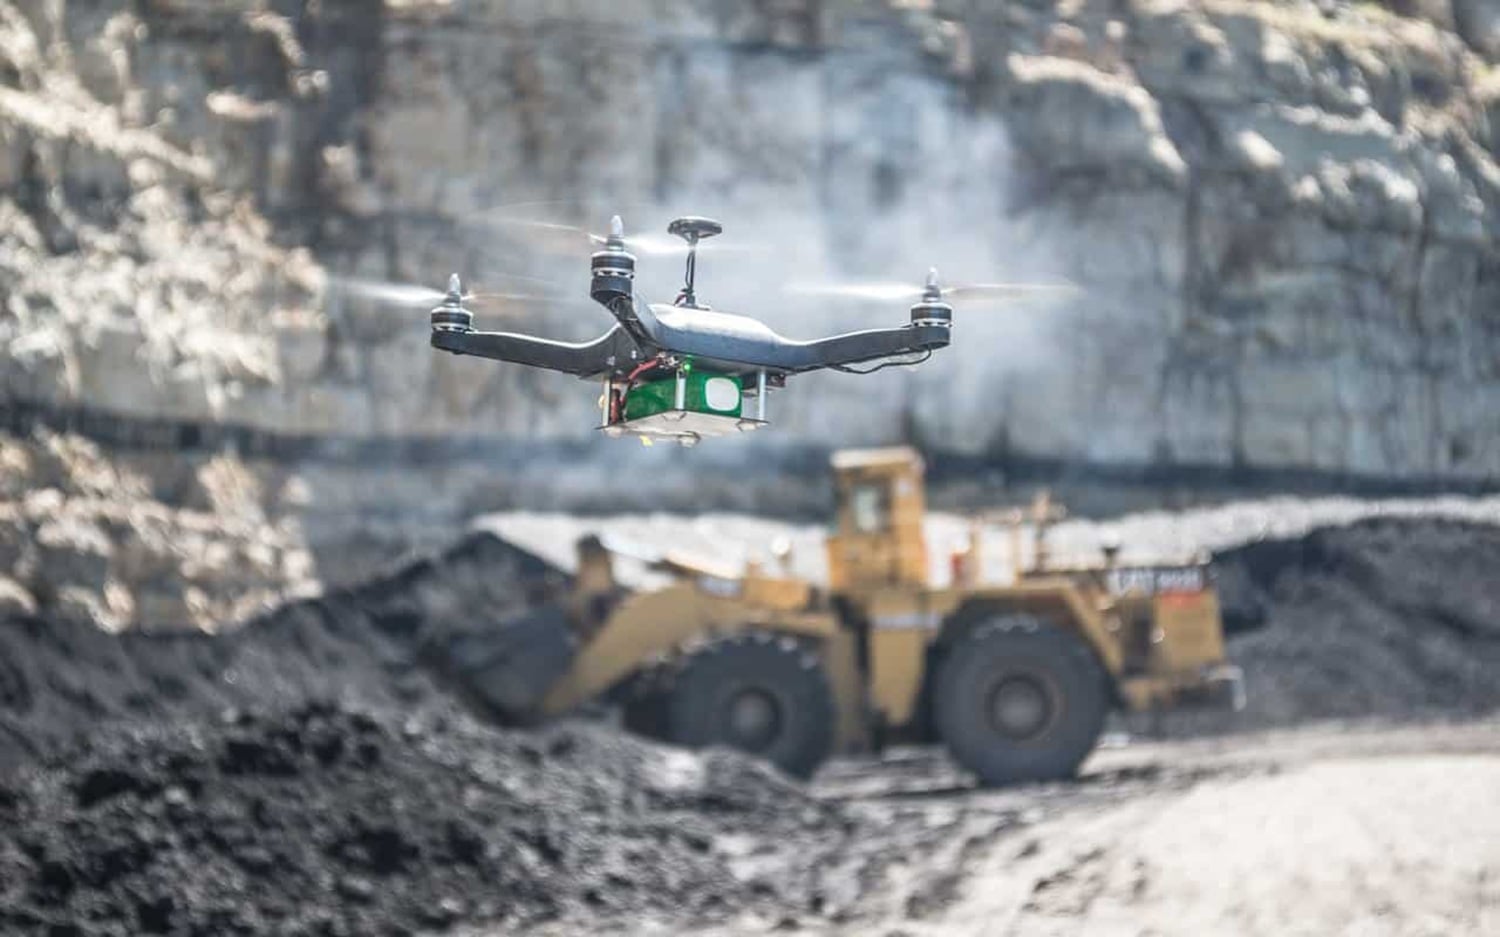
Automation has provided a boost for the biggest miners’ major iron ore, coal and copper profit engines over the past decade and a half. Now momentum is building for wider adoption of “open autonomy” and democratised automation with AI-driven edge control of machines.
Deswik CEO Andrew Pyne, a veteran of the mining tech space, believes the holy grail of zero-entry mining is getting closer. “There is a mine in China that’s already zero-entry automated. It’s fully automated coal mining and it’s fully electric, battery electric vehicles where the battery gets changed out faster than a fuelling cycle on a haul truck,” he says.
Elsewhere, automation of production haulage vehicles has “been a reality for a number of years in mining”.
“However, the current version of automation technology has limits to the environments in which they can be effectively deployed,” Pyne says. “Over the new few years we expect to see a new generation of technology providers enter the mining industry and expand the applicability of automation in mining. These new technologies will be leveraging emerging level five, fully-automated capabilities to augment the tremendous value already delivered by the OEM AHS solutions.”
Silicon Valley firm Applied Intuition, which recently formed an alliance with Komatsu, thinks a $1.6 billion mining vehicle autonomy market can expand eightfold by 2031.
“It all sounds a little SkyNet but over 90% of operating mines today are investing in AI and autonomous fleets and the number of digital offerings to optimise operational efficiencies, provide digital frameworks and ensure proactive maintenance and reliability is growing apace,” said Laura Tyler, who spent nearly 20 years in senior management roles at BHP and was most recently CEO of Adriatic Metals.
“The next step into quantum computing, although in its early stages, is poised to revolutionise many aspects of work across industries.
“It will solve problems that are currently beyond the reach of classical computers and will have profound implications for how we work, think and collaborate. It will accelerate problem-solving in complex fields such as materials science to improve energy production, orebody and rock mass modelling and mineral extraction; it will solve optimisation problems to revolutionise logistics, supply chains and resource allocations, including production schedules re-optimised in real-time to reduce cost and waste.
“AI and ML potential will be expanded as quantum computing speeds up the training of AI models we currently use in autonomous vehicles and robotics.”
Others are more cautious about the rate of progress. Danie Burger, chief advisor underground technology with Rio Tinto, says “the technology is just not there yet” for zero-entry mining.
“Approximately 76% of the entire mining process is still very much a manual process using some form of mechanisation [with] 24% of the remaining processes either automated with tele-operations, which accounts for about 21%, and full automation the remaining 3%,” he says.
“We should be investing in technologies that reduce or eliminate exposure of our underground personnel [to hazards].”
Steve Coughlan, co-founder and executive chair of the world’s largest underground hard-rock mining contractor, says remote-controlled and semi-automated machines and systems are boosting safety in the industry’s most productive mines. The Byrnecut leader sees significant progress coming over the next decade or two. “It’s a question now of how you build intelligence into the automation. You can get in a car without a driver in the US now and it will take you from A to B. That vehicle is making decisions using artificial intelligence to drive you between two points and not run over people or hit another vehicle.”
The game changer for mining “is adapting that kind of logic into our underground automation”.
Recycling an old story
Strategic and venture funding is flowing into the urban mining and waste reprocessing areas. That could become a torrent in the next decade.
Amerigo Resources is a little-known Canadian company formed 40 years ago that quietly started mining the tailings of the world’s biggest copper producer in the early 1990s. Sans the gravitas of a primary copper and molybdenum producer Amerigo has certainly had its ups and downs as a public company. But its stock has hit a new zenith, pushing its market value past C$1 billion, and copper prices aren’t the only reason.
CEO Aurora Davidson says Amerigo turns the daily waste material of the world’s largest underground copper mine, El Teniente, into circa-US$200 million of annual revenue. “We replace the world’s need for a 30,000 tonnes per annum copper mine.”
On a somewhat grander scale copper major Freeport-McMoRan wants to produce 360,000tpa of copper through reprocessing of chalcopyrite (sulphide) waste material at its US mines using new leaching and recovery technologies. Others are going down the same path, looking to unlock value from waste by achieving adequate metal recoveries to make the reprocessing economically viable.
“We have 40 billion pounds of copper locked in waste stockpiles,” Freeport chief sustainability officer Bill Cobb told the Resourcing Tomorrow conference in London in December. “We are at about 200-to-300 million pounds of copper a year [and] our target is 800 million pounds. That’s a new major copper mine and it's basically capturing waste material at the mine site.”
Others are taking a similar view of the world.
Garry Korte, CEO of Australian iron ore producer Hancock Prospecting, told the 2026 Future Minerals Forum in Saudi Arabia the company’s upgraded wet high intensity magnetic (WHIM) separator plant at its flagship Roy Hill operation was recovering a further five million tonnes of ultra-fine iron ore previously going through to tails.
“At Roy Hill we’ve already mined in excess of 400Mt of lower-grade material which is sitting on stockpile,” Korte said. “We’re evaluating at the moment dense media separation to be able to upgrade that material. It’s a huge resource already sitting on a stockpile; it’s lower cost to utilise that material [with] less dewatering. It makes a lot of sense to minimise the [overall operational] footprint.
“For us it’s about making the most of the orebody.”
An Australian mine waste expert, Sustainable Minerals Institute associate professor Anita Parbhakar-Fox says an estimated 100 gigatonnes of mine waste is being produced each year around the world and lower average mineral grades and higher material movement rates mean the rate is likely to climb. “Taking just one commodity, copper, tailings production [is predicted] to increase from 4.3Gt a year in 2020 to 16Gt/y in 2050. In total, 858Gt of mine waste could be produced for this metal alone up to 2050,” Parbhakar-Fox says.
Freeport business Atlantic Copper is also aiming to produce copper, gold, silver, platinum, palladium and tin from up to 80,000tpa of pre-processed waste electrical and electronic equipment (WEEE or e-waste) metal shreds at its US$540 million CirCular project at Huelva in Spain. The venture is due to be launched this quarter.
Heavyweight miners investing in sulphide leaching, waste reprocessing and metal recycling tech and tech companies have been joined by an increasing number of institutional investors and high net worth individuals.
ASX-listed Metallium, which has quadrupled in value in the past 12 months, says e-waste is the world’s fastest-growing waste stream, rising at double-digit rates and containing vast quantities of precious and strategic metals. The United Nations says only about a quarter of the more than 62 million tonnes of e-waste produced by people annually is being recycled in an environmentally sound way.
Metallium, targeting the US market and a Nasdaq listing in 2026, is commercialising its Flash Joule Heating (FJH) electrothermal method of extracting metals from e-waste, scrap and primary ores after raising about US$100 million of equity funding in the past year or so. “Unlike conventional smelting or leaching, FJH applies ultrafast electrical energy to unlock or volatilise metals, delivering rapid recovery without acids, tailings or long thermal cycles,” it says.
US-based Cleantech Group’s Diana Rasner says mining and refining processes for most minerals are among the world’s most energy and emissions-intensive industrial activities. They are frequently linked to water stress, toxic chemical byproducts and large-scale land disturbance. “This dual vulnerability – geopolitical and environmental – is driving a surge of innovation focused on reshaping the supply chain,” she said.
Companies such as Metallium, Vancouver-based pH7 Technologies, Chile’s Ceibo and American firms Nth Cycle, DISA Technologies and Phoenix Tailings are among a wider cohort that has raised hundreds of millions of dollars in recent years to advance waste mineral and metal recovery.
Shoring up sovereign supply chains
The US is miles behind Australia, Canada, Sweden and probably China as a mining tech incubator, but well ahead as a source of private technology funding that is now spilling into the mining and metals tech arena.
Not trumpeted anywhere near as loudly as other US government critical minerals initiatives, the Department of Energy (DOE) got in on the act in September 2025 with its “Mine of the Future” funding – $80 million for mining technology proving grounds and $15 million of research funding – that did signal an awareness that what was left of America’s mining industry was generally a laggard in the high-tech mining stakes.
That is, behind the game in the longer term when domestic mining and refining subsidies run their course.
Peter Bryant, a long-time government and industry adviser and founder of the Washington-based Key Minerals Forum, thinks the DOE needs to see the global mining technology landscape and set strategy through a “national strengths” lens.
“The DOE model that served it well in new energy sources benefited from looking forward into the future at renewable energy and building methodically towards deployment,” he says.
“However, with minerals DOE is 20 years behind the problem and so a more accelerated, bolder and nimbler approach is needed.
“While the US is a manufacturing and innovation superpower, allies like Australia, Chile and Canada are extraction superpowers.
“It follows that the US will most effectively focus its investment in innovation, leveraging America’s comparative advantage in advanced manufacturing, materials science and digital technologies. Then, as a global leader, the US can put this innovation capability to work in supercharging resource-rich allies to create progress the US alone cannot achieve.”
Bryant says global competition continues to heighten the stakes. The US is in competition with the rest of the world but China holds a dominant position in mineral processing and refining, “having invested for decades in infrastructure and applied innovation”.
“Without a comparable catch-up the US risks losing not just competitiveness but also supply chain security.”
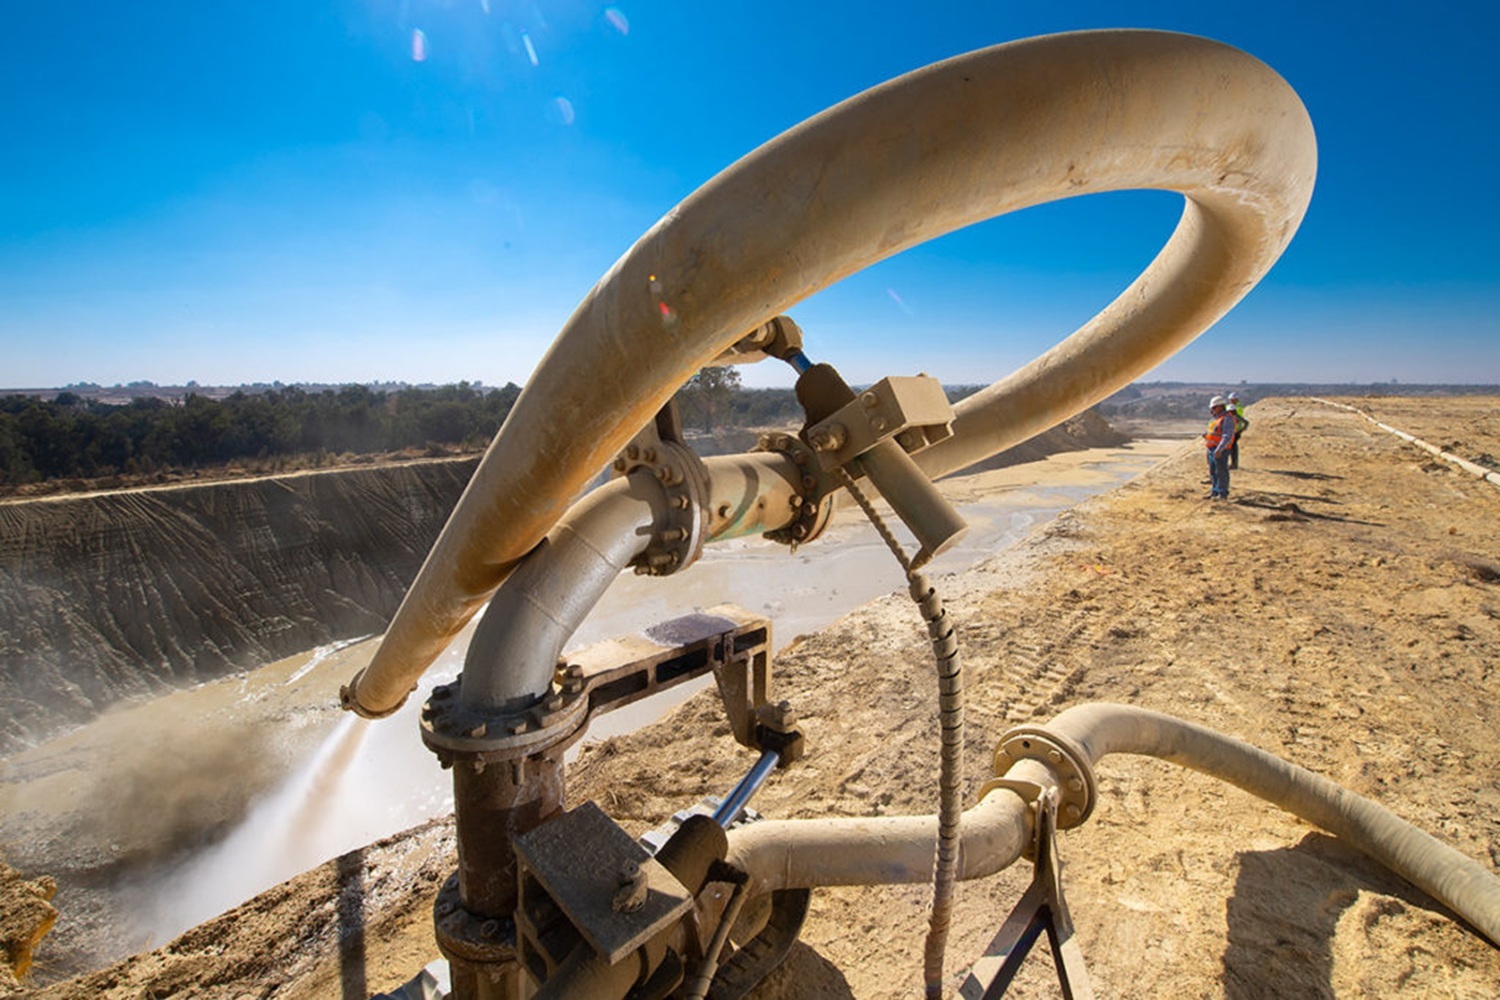
Water pressure rising
Joanne Emerson Taqi, a partner in law firm White & Case’s Sydney office, says mining and metals sit at the heart of what is emerging as a defining constraint of the 21st century.
“In the US alone mineral extraction consumes an estimated four billion gallons of water a day, equivalent to the daily use of 13 million households,” she says.
“Downstream processing and refining operations add further to this demand, significantly increasing the sector’s total water footprint.”
The huge demand for water is said to have created a mine water management market worth an estimated $8 billion that could grow to $12.5 billion by 2033. Emerson Taqi says that is currently dwarfed by more than US$20 billion of water-related financial impacts from poor water management.
“Looking ahead, the challenge is set to intensify,” she says.
“Global mining investment is projected to rise by an additional $150 billion annually between 2025 and 2029, placing even greater pressure on the sector to maintain high production levels. Mining and metals companies, which are increasingly reliant on water-based processes to maximise output, must also compete with agricultural, industrial and domestic users for scarce water resources – a vulnerability investors have identified as the greatest risk facing the industry.”
Untapped, a report on strategic mine water management and relevant technology sponsored by mineral processing equipment manufacturer Weir, says about 16% of the world’s land-based critical mineral mines, deposits and districts are located in highly water-stressed areas. It says some 40% of the world’s copper supply is located in areas of high water stress, such as Australia, Chile and Peru. “Copper is a thirsty mineral to process in terms of water consumption per tonne of metal produced,” the report says. “Adopting innovative flowsheets and an end-to-end approach could reduce water consumption per tonne of copper produced at a typical copper mine by as much as 78%.
“As a sector we need to shift the way we think about water. Rather than treating it as a constraint or risk to be managed we need to value it in the same way that we value energy and carbon. That means understanding its long-term social and environmental value as well as its immediate economic value.”
Americas mining contracting and engineering company Stracon says mining companies are investing in closed-loop water systems, desalination plants and community water partnerships. “Vale’s Capanema mine in Brazil, which recycles 99% of its water, illustrates how water management has become central to maintaining a social licence to operate,” it says.
Emerson Taqi says Vale has also invested heavily in dry processing techniques at its Brazilian iron ore mines, with 90% of the company’s core Northern System production hub in Para now using dry processing technology. “They aim to fully eliminate water use for iron ore processing at their Carajas mining complex by 2027,” she said.
Emerson Taqi says rapid development of technology “has become the most powerful tool for addressing mining and metal’s water challenges, with water treatment and recovery technology at the forefront”.
“In downstream processing, techniques such as metal-specific ion exchange, solvent extraction and membrane filtration are increasingly being deployed to reclaim water from processing streams and reduce contamination risks. In extraction and beneficiation, dry processing and high-efficiency filtration are being adopted to minimise water use at earlier stages.
“Advancements in desalination technology are also playing a critical role, where new approaches – such as thermodiffusion methods, which use moderate heat to separate salt without electricity – have improved efficiency and reduced costs of infrastructure.
“Not only are new technologies improving existing processes, but entirely new areas are emerging through the integration of data and artificial intelligence.
“Digital tools are redefining how water is tracked, analysed and managed across mining operations. For example, the use of Internet of Things sensors and data analytics for smart water management allows continuous monitoring of water quality and flow, automated detection of contaminants and predictions of when treatment system maintenance is required to prevent leaks.
“By integrating these data streams onto central dashboards, operators can maintain a better process control to holistically optimise water usage.”
Click and read the Ten major mining tech trends in 2026: Part 2 here.
Technology and Innovation
Investment and Finance
Mining
Environmental, Social, and Governance (ESG)
Workforce and Culture
International Mining and Resources Conference + EXPO
It looks like you're trying to log in with an email address that isn't registered with our system. Registering is both quick and easy! Just click the button below to sign up.
NOTE: If you're trying to access presentations or content associated with your exhibition attentance please sign up with the email address used for the exhibition participation.
Submitting...
It looks like you're opted-out for emails
The email address you have entered has opted-out of email communications from us.
You will need to opt back in to receive a response from this form submission.
PLEASE NOTE: This action will only opt you back into the email communications you specify when you manage your email preferences. You will be able to choose the type and frequency of communications you receive from us.
If you would prefer not to opt back in please contact us directly via email or phone.
Share
Copied to clipboard
Accessibility options
Font size
Contrast
Beacon is committed to providing a digital experience that is accessible to all users, including people with disabilities.
As such, we are continually working to improve the accessibility of our website by adhering to the Web Content Accessibility Guidelines (WCAG).
Some content on our website may not be fully accessible. We are working to address these issues.
If you experience any accessibility issues with our website, please contact us at [email protected]